Is the S&P 500 ACTUALLY Overvalued?
The creator argues that whether the US stock market is in a bubble is hard to say, since the answer depends on which metric and index you look at. They narrow the question to whether the S&P 500 specifically is expensive by historical standards, walking through valuation measures like the Shiller CAPE ratio, trailing and forward P/E, and the PEG ratio, and comparing the S&P 500 to the S&P 400, S&P 600, and the MSCI ACWI ex USA index. The analysis rests mostly on the creator's own calculations and index level data, with a handful of named sources cited along the way: a Bloomberg diagram on circular AI deals, S&P Global's index coverage figures, Yardeni Research's earnings forecast chart, and MSCI's index composition. The creator stops short of declaring the market a bubble or not, instead warning against overconfidence in either the bubble thesis or the belief that Sam Altman and other AI executives will deliver transformative success.
Thesis [01:17]: whether the stock market as a whole is in a bubble is hard to determine because it depends on what you look at.
- Argument [00:21]: many people are worried the US stock market is in a bubble.
- Argument [00:27]: tech companies now dominate major indices while spending hundreds of billions on AI infrastructure for ultimately unprofitable AI companies, amid rising oil prices, treasury yields, and inflation.
- Argument [00:42]: the stock market keeps reaching new all time highs, leading many to conclude it must be in a bubble.
- Unsourced claim [01:00]: SpaceX set IPO records and broke into the US top 10 largest market caps despite revenue not cracking the top 200, priced at $135 a share in a $75 billion IPO.
+ 40 more takeaways
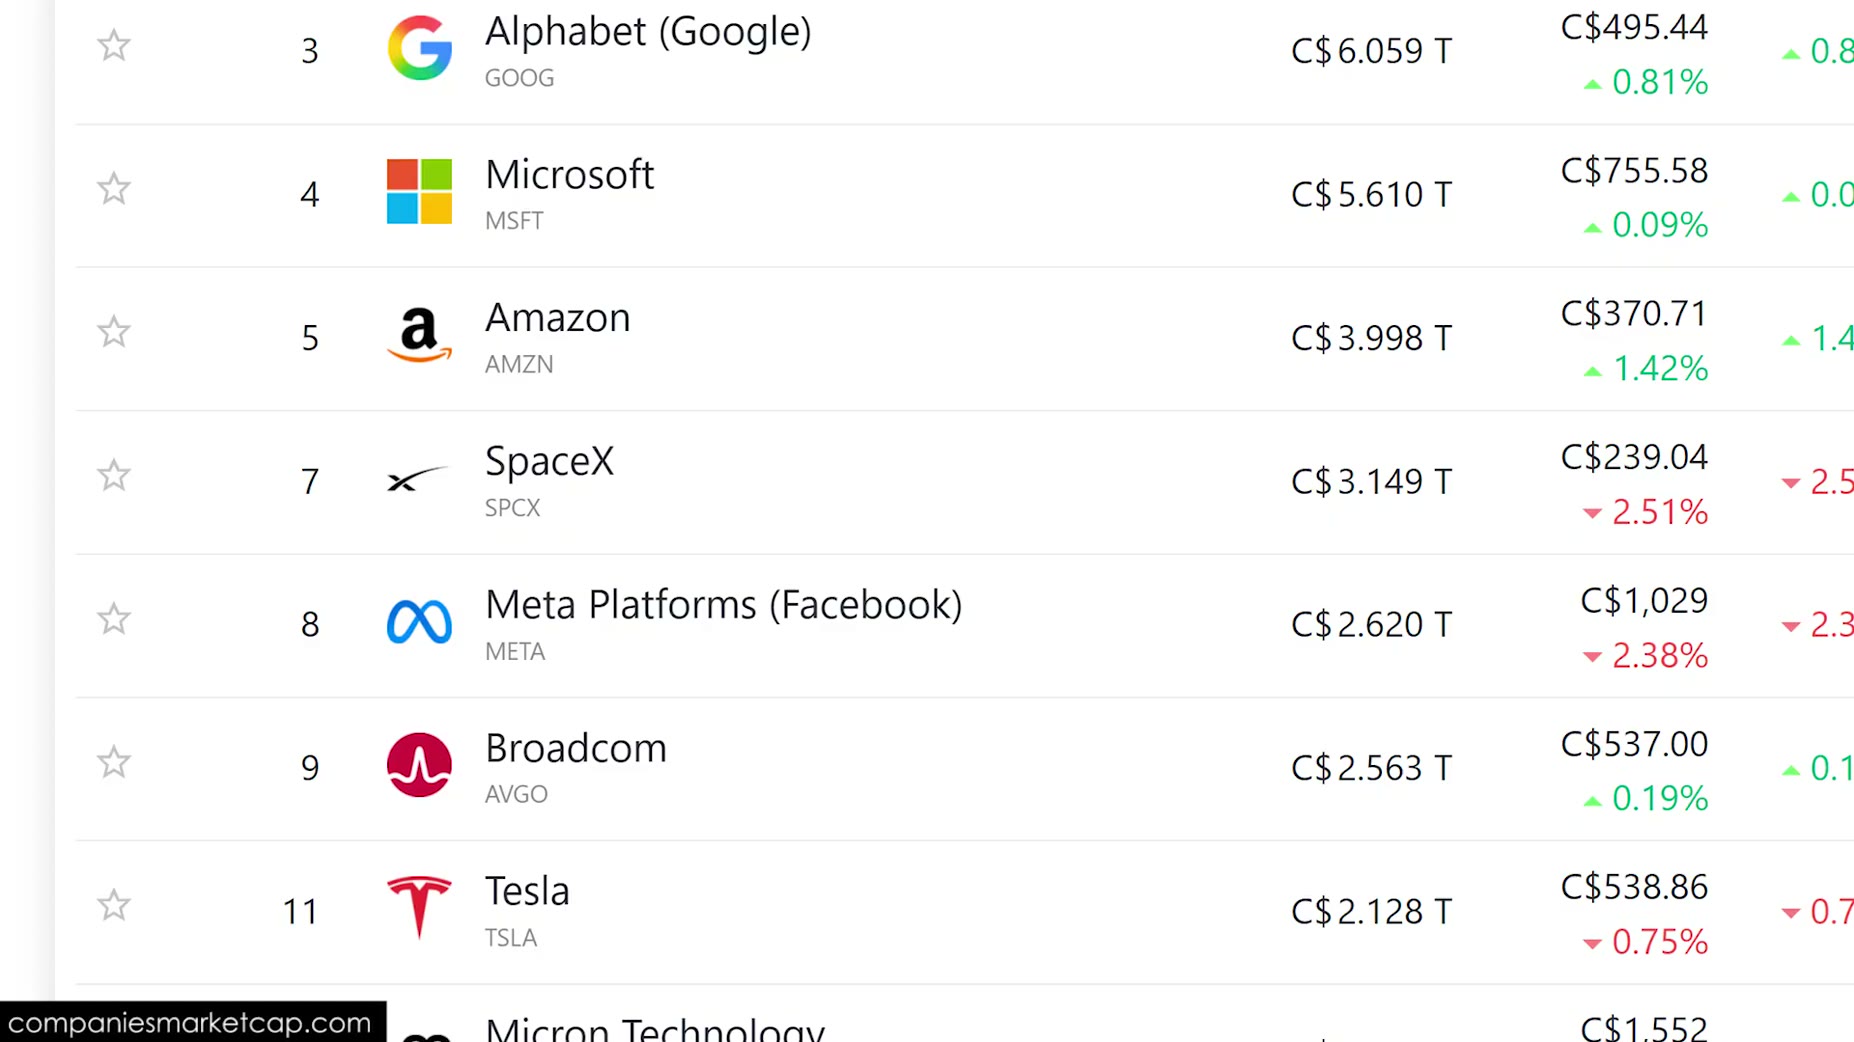
- Unsourced claim [01:04]: market cap figures cited are Alphabet at $6.059 trillion, Microsoft at $5.610 trillion, Amazon at $3.998 trillion, SpaceX at $3.149 trillion, Meta at $2.620 trillion, Broadcom at $2.563 trillion, and Tesla at $2.128 trillion.
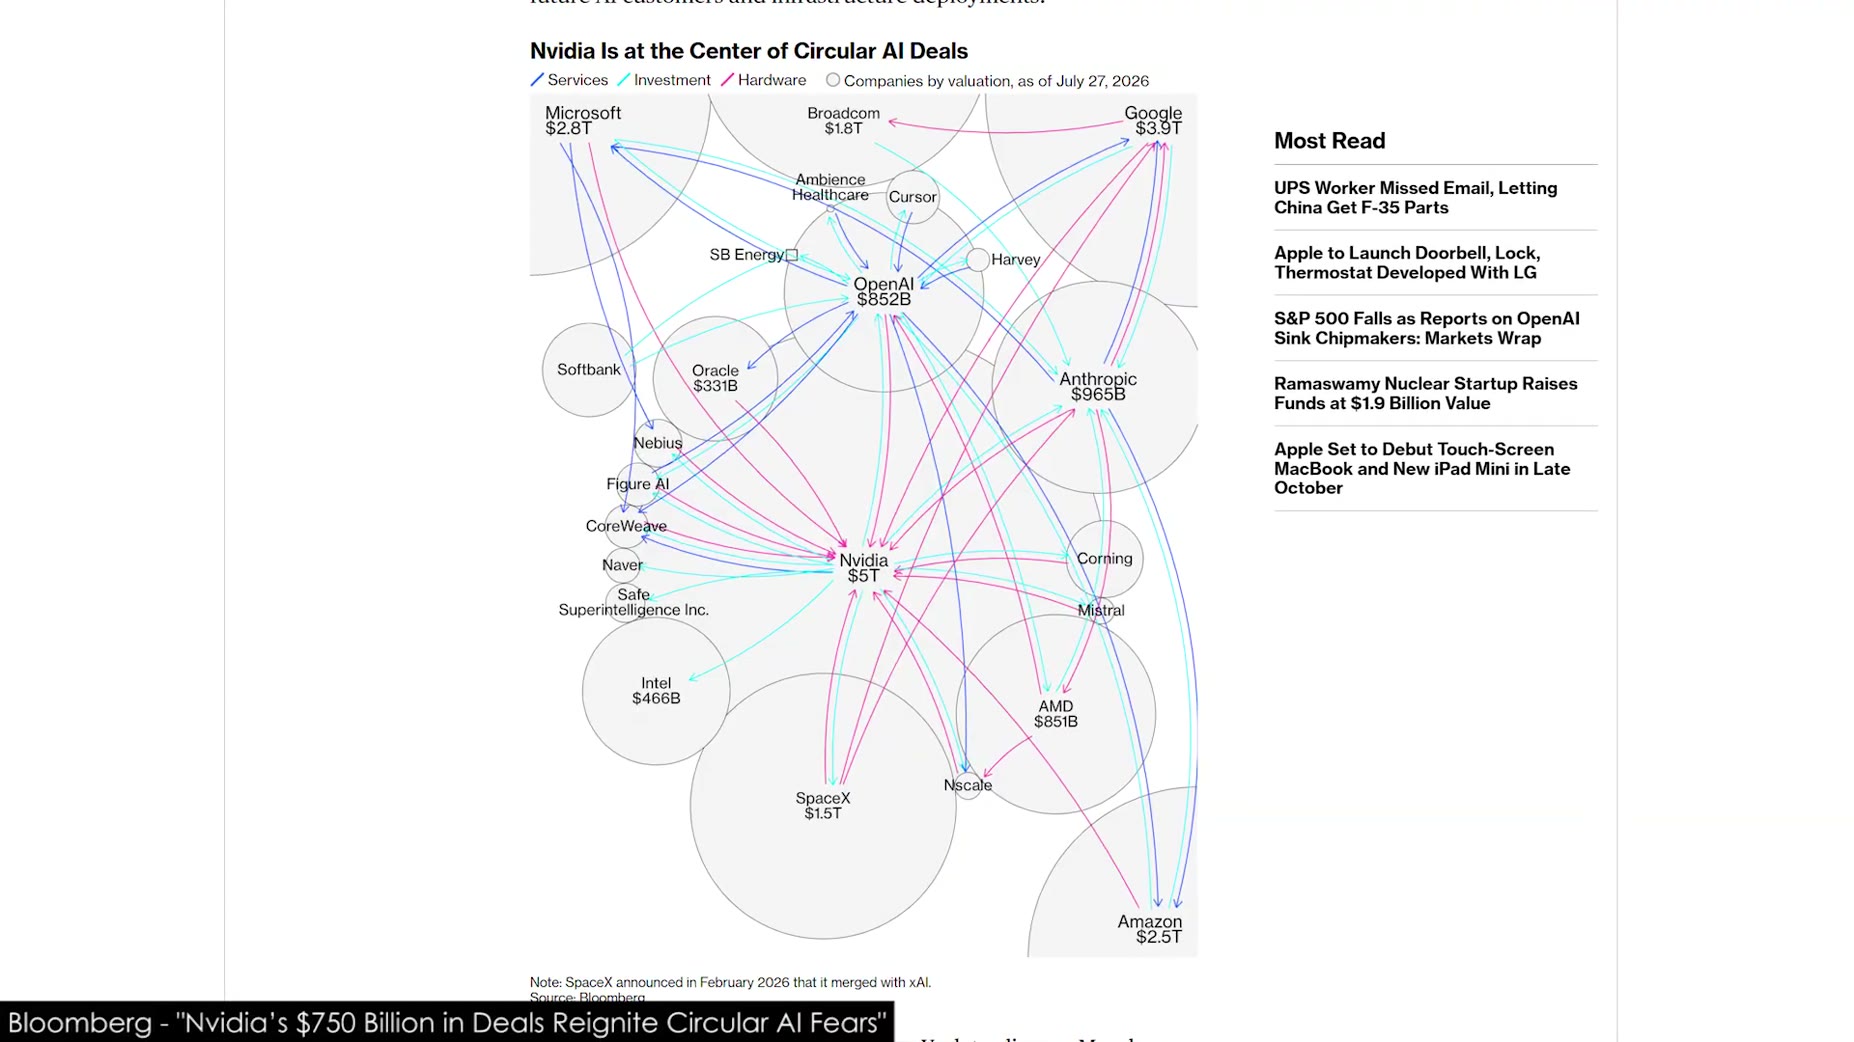
- Sourced claim [01:14]: a Bloomberg article and diagram titled 'Nvidia Is at the Center of Circular AI Deals' notes that SpaceX announced in February 2026 that it merged with xAI.
- Prediction [01:41] (no timeframe stated): the creator predicts the outcome lands somewhere between a utopia where AI powered robots let everyone retire rich and an Armageddon where AI takes over and the economy collapses.
- Argument [02:03]: the video narrows its focus to whether the S&P 500 specifically is expensive by historical standards.
- Argument [02:54]: the S&P 500 is made up of 500 of the largest US stocks by market cap but has other inclusion criteria, like time and earnings requirements, that currently exclude companies like SpaceX.
- Sourced claim [03:12]: per S&P Global, the S&P 500 covers about 83% of the entire US stock market's capitalization.
- Argument [04:23]: the video's valuation metric is the price to earnings (P/E) ratio, stock price divided by earnings per share, aggregated as a market cap weighted average across all 500 companies.
- Unsourced claim [04:52]: the Shiller CAPE ratio is currently above 40 times, a level not seen since the dot-com bubble, and is approaching a new all time high.
- Argument [05:21]: CAPE smooths earnings by dividing price by average inflation-adjusted earnings over the past 10 years, reducing year over year volatility and short-term cyclical skew.
- Argument [05:47]: a drawback of CAPE's smoothing is that it can understate the impact of rapid recent earnings growth and overstate valuation, which the creator says is happening now.
- Unsourced claim [06:03]: in Q3 2026, S&P 500 earnings grew nearly 30% year over year, the third straight quarter above 25% growth.
- Unsourced claim [06:15]: the 25-year average annual earnings growth rate for the S&P 500 has been 6.4%.
- Argument [06:25]: much of the short-term earnings growth is tied to the AI buildout, with data centers being built at a rapid pace in the US.
- Argument [06:45]: if AI driven growth is sustained, trailing PE (using only the past 12 months of earnings) may be a better measure than CAPE.
- Unsourced claim [07:02]: the current S&P 500 trailing PE ratio is 26.61, elevated but well below the dot-com bubble peak.
- Unsourced claim [07:35]: the S&P 500 forward PE, using next 12 months of consensus earnings estimates, is around 19 times versus a long-term average of 16 times and a dot-com peak of 25 times.
- Argument [08:50]: the forward PEG ratio, forward PE divided by 5-year estimated earnings growth, suggests the S&P 500 is actually cheap; ratios above 1 are considered expensive and below 1 cheap.
- Unsourced claim [09:25]: the S&P 500's PEG ratio suggests it is cheap, in fact the cheapest it has been in decades.
- Unsourced claim [09:43]: the consensus 5-year earnings growth estimate has surged over the past two years and currently sits at 27.3%.
- Unsourced claim [10:22]: the S&P 400 and S&P 600 trade at forward P/E ratios of around 14 to 15 times versus the S&P 500's nearly 20 times.
- Unsourced claim [10:38]: PEG ratios cited are S&P 400 at 0.8, S&P 600 at 0.96, and S&P 500 at 0.69, the lowest of the three.
- Sourced claim [11:03]: the MSCI All Country World Index ex USA covers 22 developed and 24 emerging countries, capturing about 85% of global equities outside the US.
- Unsourced claim [11:22]: the MSCI ACWI ex USA index has a forward P/E of 12.5 times, fairly cheap by historical standards, with earnings estimates surging.
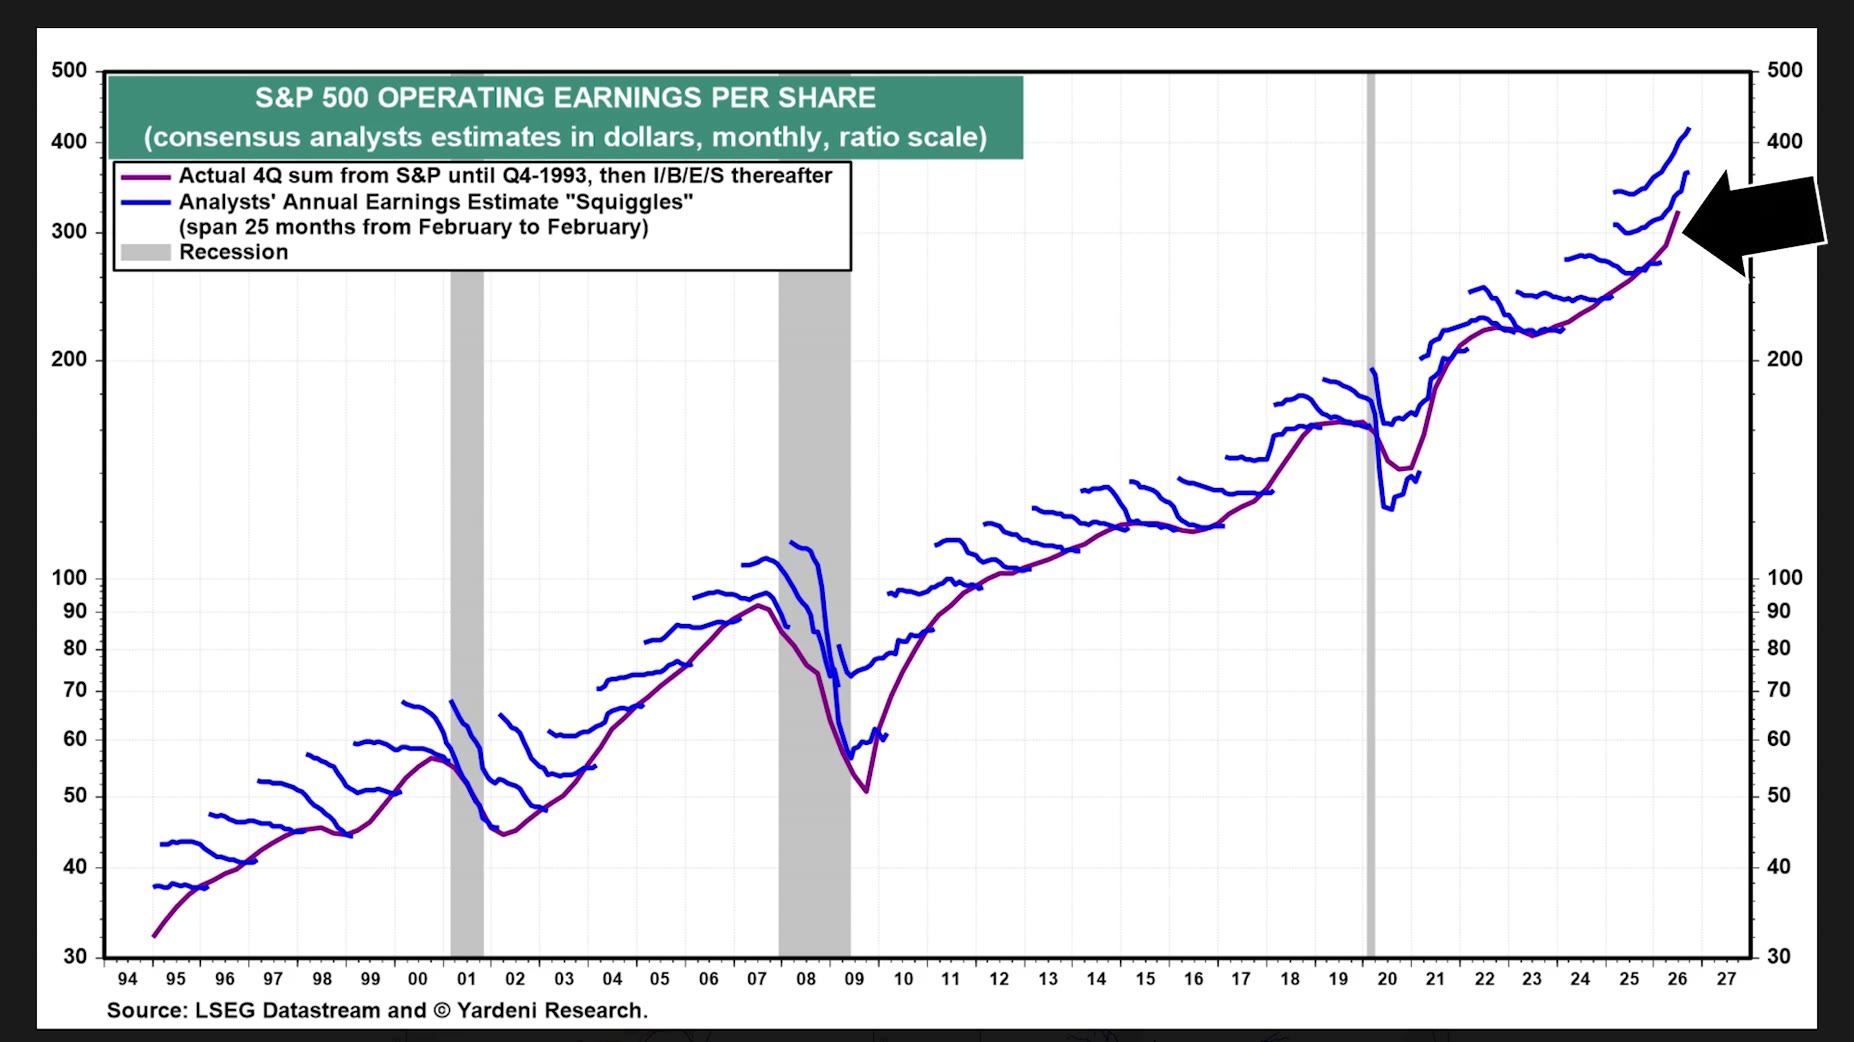
- Sourced claim [12:21]: Yardeni Research has a chart called 'squiggles' that shows how actual S&P 500 operating earnings per share compares to past analyst forecasts over a roughly 25-month period.
- Argument [12:53]: analysts tend to be too optimistic during upward slopes, with most squiggles trending downward even as actual earnings rise.
- Unsourced claim [13:10]: the Magnificent Seven (Google, Amazon, Apple, Meta, Microsoft, Tesla, Nvidia) represent about a third of the S&P 500.
- Unsourced claim [13:31]: the Magnificent Seven carry above-average valuations compared to the other 493 S&P 500 constituents.
- Unsourced claim [13:39]: OpenAI and Anthropic are not yet publicly traded but could skew valuations further, given insider reports of highly unprofitable operations.
- Unsourced claim [13:57]: forecasted S&P 500 earnings growth appears to come mostly from cost savings rather than revenue growth.
- Unsourced claim [14:09]: forecasted S&P 500 revenue growth is only 15.6%.
- Unsourced claim [14:50]: much AI spending, like chips and data centers, is recorded as capital expenditure on the balance sheet rather than as an income statement expense, raising questions about whether earnings understate true costs.
- Unsourced claim [15:27]: there are also questions about whether the chip lifespan assumptions behind this capex accounting are accurate.
- Unsourced claim [16:55]: on a forward basis, the S&P 500 equity risk premium today is around 4%, lower than most of history but higher than during the dot-com bubble.
- Argument [17:05]: a low equity risk premium means investors take on stock market risk for a lower marginal return over treasury yields.
- Unsourced claim [17:15]: the 10-year treasury yield has spiked recently, and higher treasury yields act as gravity on stock market valuations.
- Argument [17:26]: rising yields can pull investor capital out of the stock market, which could matter for AI companies relying on investor capital to fund growth.
- Counterpoint [17:37]: the creator notes the counterargument that AI has remarkable upside these metrics can't capture.
- Counterpoint [17:43]: the creator says the point isn't to argue for market timing but to show how complicated it is to assess even one basic facet of the situation.
- Counterpoint [17:55]: the creator cautions against overconfidence in either the bubble thesis or the belief that Sam Altman and other AI executives will deliver transformative success.
- Ask: not stated.
How this brief was shaped: Trend Commentary / Opinion Essay · confidence Low
Single narrator argues a thesis against the AI bubble narrative using quantitative market data like PE ratios and market cap weighted averages, which is a claims-and-evidence opinion essay rather than a quote-driven exchange. The OCR sample is mostly unrelated suggested video thumbnails, not on screen content from this video, so the route leans on the transcript.
The lens sets this brief's structure, never its facts — every claim is held to the same citation and fact-check standard.